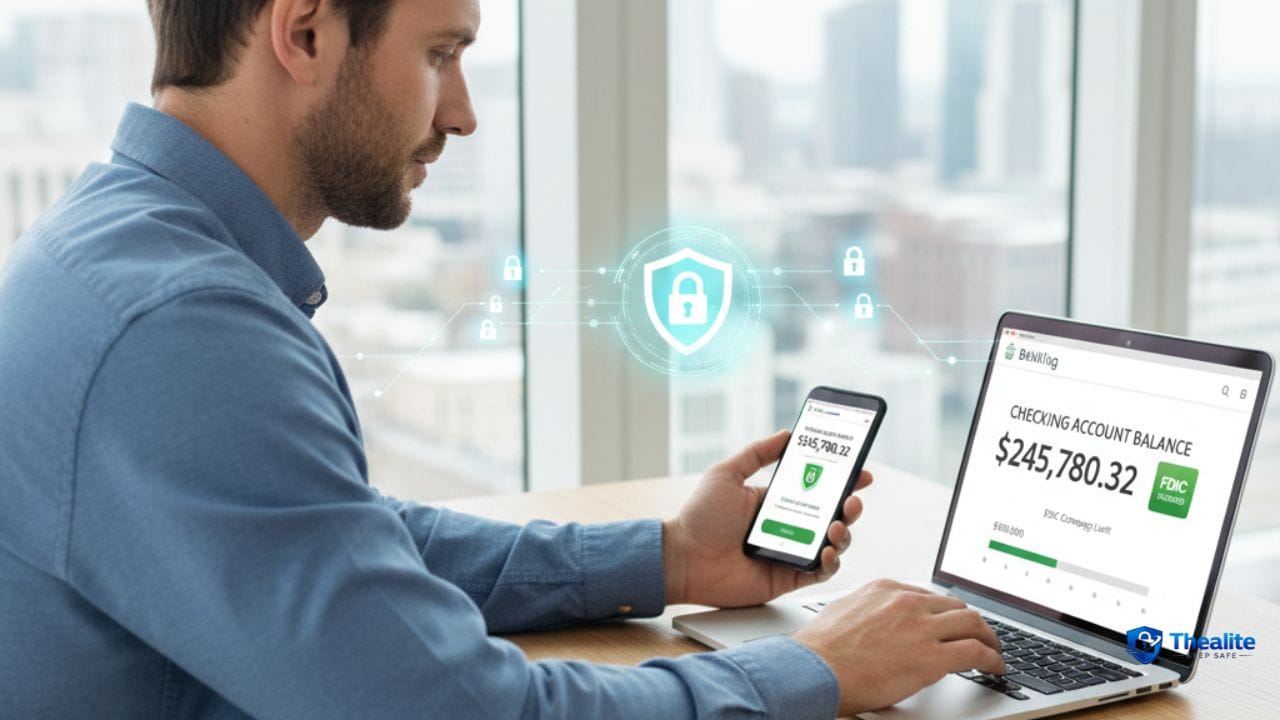
Yes, it’s generally safe to keep money in a checking account—especially if your bank is FDIC‑insured (or your credit union is NCUA‑insured) and your total deposits stay within the insurance limit. The bigger everyday risk isn’t the bank failing—it’s fraud, scams, or account takeover. So the safest setup is: insured institution + strong login security + alerts.
Safety #1: Deposit Insurance (What Happens if the Bank Fails?)
In the U.S., most checking accounts at insured banks are protected by federal deposit insurance. FDIC insurance covers deposits up to $250,000 per depositor, per insured bank, per ownership category. That means your checking + savings at the same bank (in the same ownership category) are usually added together.
If your checking account is at a federally insured credit union, NCUA share insurance works similarly and also protects up to $250,000 per share owner, per insured credit union, per ownership category.
How to Know If Your Checking Account Is Insured
Do a quick check before you store larger amounts:
- Look for “Member FDIC” on a bank’s website/app or branch signage.
- For credit unions, look for NCUA/NCUSIF coverage (“Federally insured by NCUA”).
- If you’re unsure, use the FDIC/NCUA official tools or contact the institution directly.
What If You Have More Than $250,000?
If you keep more than the insurance limit at one institution, that doesn’t automatically make it “unsafe,” but the amount above the insured limit may not be covered if the institution fails. Many people handle this by spreading money across insured institutions or using different ownership categories (when eligible).
Simple options people use:
- Split funds across two FDIC‑insured banks (coverage applies at each bank).
- Use additional ownership categories if you qualify (example: joint vs. individual).
- For long-term cash, consider insured savings or money market deposit accounts (still deposits).
Safety #2: Fraud Risk (The More Common Problem)
Most losses linked to checking accounts come from fraud: phishing texts, fake bank calls, stolen debit cards, or someone getting into your online banking. The good news is you can reduce this risk a lot with a few habits.
Best Practices to Keep Your Checking Account Safer
- Turn on real-time alerts for transactions and logins.
- Use a unique strong password and enable multi‑factor authentication (MFA) when available.
- Don’t log in from links in texts/emails—open the bank app or type the address yourself.
- Lock your debit card in the bank app when you’re not using it (many banks offer this).
- Review your transactions often so you catch issues fast.
For a full step-by-step guide, read:
How to keep your bank account safe online
How Much Money Should You Keep in Checking?
Safety-wise, checking is fine for everyday use. The more practical question is: how much do you want sitting there? Checking accounts often earn little or no interest, so keeping a very large balance there may cost you growth over time.
A common approach is:
- Keep enough for 1–2 months of bills + a small buffer for surprises.
- Keep emergency savings in an insured savings or money market deposit account (still insured deposits).
- Use a separate “spending” account if you want extra protection (smaller exposure if fraud happens).
Situations When Checking Might Feel “Not Safe”
These are warning signs that you should tighten security or change how you store money:
- You regularly click links in texts/emails to log into banking.
- Your phone number/email isn’t secured with MFA (easy account resets).
- You use the same password on multiple sites.
- You keep large balances but have no alerts enabled.
- You’ve had fraud before and didn’t change habits afterward.
What to Do If You See an Unauthorized Charge
Act quickly. Faster reporting usually means less hassle.
- Lock your card/account in the app (if available).
- Call your bank using the number on the back of your card (not from a text message).
- Change your online banking password and secure your email.
- Review recent transfers and payees; remove anything you don’t recognize.
- Keep notes: dates, amounts, and who you spoke to.
FAQs
Is it safe to keep all my money in checking?
It can be safe if you stay within FDIC/NCUA limits and have strong security. But it may not be the best setup because checking often earns little interest and exposes a larger balance to everyday fraud risk.
Is my money safe if the bank goes under?
If your bank is FDIC‑insured (or your credit union is NCUA‑insured) and you stay within coverage limits, your deposits are generally protected.
Does FDIC cover fraud or stolen money?
FDIC primarily covers deposits if an insured bank fails. Fraud protection is handled through your bank’s policies and consumer protection rules for electronic transfers. The practical move is to use alerts and report suspicious activity immediately.
What’s the best way to reduce checking-account fraud?
MFA + alerts + never logging in from message links are the top three habits.
More “Keep Safe” Guides
Explore more guides at Thealite Keep Safe. For money safety basics, read How to keep your money safe.

As a digital marketer, she has received multiple international awards, including Campaign of the Year at the 2023 European Content Awards and Best Use of Content Marketing at the 2022 Global Search Awards. Nicai holds an MSc in Marketing (First Class Honours) from the UCD Smurfit Graduate Business School and she has also completed the Artificial Intelligence Programme at Oxford University’s Saïd Business School. She is also a contributing writer for publications such as Entrepreneur and Esquire.